Avison Young

Author: Prestige PR Data: 2026-10-28

Full steam ahead

Property investment market in Poland in Q1 – Q3 2026

Author:

Paulina Brzeszkiewicz-Kuczyńska – Research and Data Manager

Comments:

Artur Czuba – Director, Investment

Bartłomiej Krzyżak – Co-Head of Investment Department

Marcin Purgal – Co-Head of Investment Department

Gaining momentum

Market in numbers:

  • EUR 4.7 bn – total investment volume Q1-Q3 (+ 81% y-o-y)
  • 93 deals
  • Best Q1-Q3 period since 2018
  • Surge in large industrial and retail portfolio transactions

Investment market performance in Poland continued to accelerate by the end of Q3 2026, with transaction volume up by 81% year-on-year. By the end of September, total investment volume reached €4.7 billion across 93 completed transactions, reflecting a significant increase in volume while maintaining stable market liquidity. The strong performance was driven by the anticipated return of core capital and large portfolio transactions, reflected in as much as 15 deals over €100 million. Q1-Q3 2026 period result was the best in terms of investment volume since 2018.

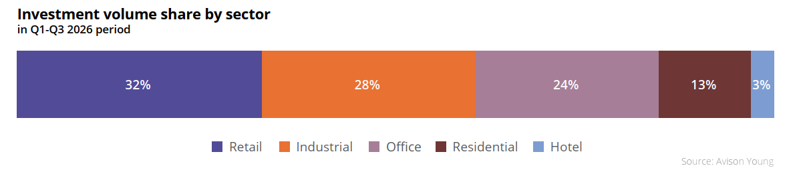
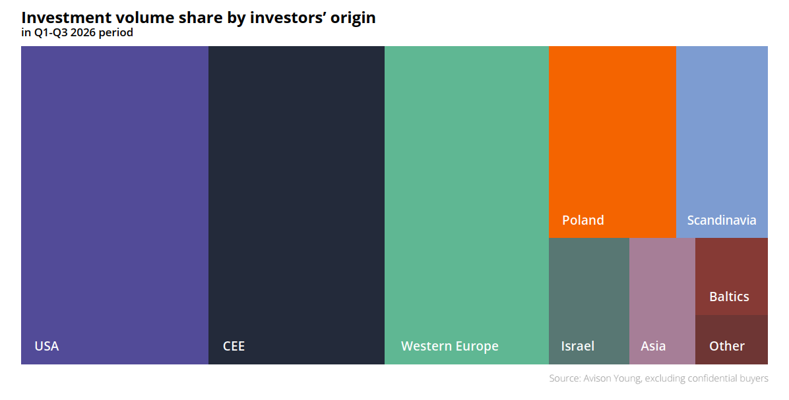
The retail and industrial sectors were the main drivers of investment activity by volume. Retail market maturity facilitated portfolio transactions, also including retail parks. Industrial results were driven by large portfolio transactions, with dominant share of US capital. Office market recorded 7 prime transactions, including Polish capital, representing 30% of the volume in this sector. Landmark deals were also completed in the PRS and hotel sectors, including the sale of the Resi4Rent portfolio and the Sofitel Warsaw Victoria hotel.

Core capital is gradually re-entering the market, targeting high-quality assets. This trend has contributed to a notable increase in average transaction volumes. Supported by favourable investors’ sentiment, resilient economic indicators and a strong deal pipeline, 2026 is set to considerably outperform the previous year.

Retail sector – expanding retail parks portfolios

Sector in numbers:

  • EUR 1.5 bn – total sector’s volume in Q1-Q3
  • 8 shopping centres sold in regional cities
  • 7/30 portfolio deals

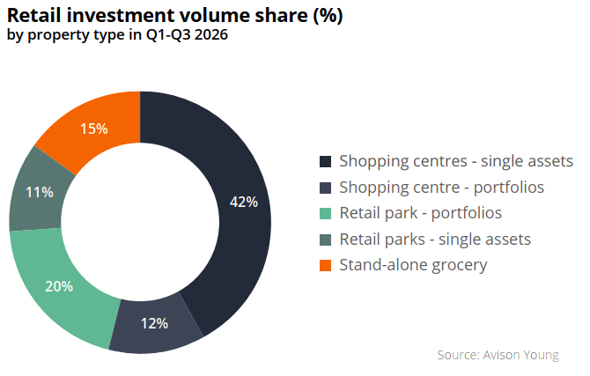
The retail sector recorded €1.5 billion in investment volume during the first three quarters of 2026, delivering its strongest year-on-year performance since 2018. Accounting for approximately one-third of total investment activity, the result was largely driven by portfolio transactions, regarding both shopping centres and retail parks, which contributed 45% of the sector’s total volume during the period.

Regional shopping centres remained a key investment target, with eight single-asset transactions completed across Poland, including the landmark sale of a 70% stake in Posnania to Trigea Real Estate Fund. Retail parks also continued to attract strong investor interest, with the growing maturity of this asset class supporting an increasing number of portfolio transactions. Such deals enable investors to gain immediate market exposure and operational scale, while allowing vendors to maximise value through efficient portfolio disposals.

“Avison Young professionals brokered 4 retail transactions completed so far this year, including all retail formats. Our track record includes the third largest retail park portfolio transaction on the Polish investment market, namely Vendo Park Portfolio acquisition by Star Capital Finance and Generali. We also brokered the disposal of Galería Pestka in Poznań as well as retail parks in Mysłowice and Błaszki. The diversity of investment opportunities across the Polish retail market continues to support strong liquidity and broad investor interest.” – Artur Czuba, Director, Investment Department

Industrial sector – market polarization

Sector in numbers:

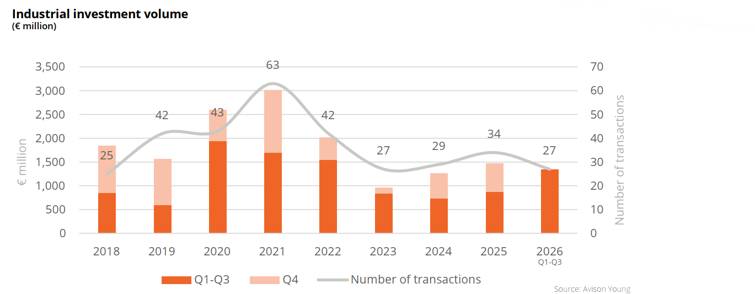
  • EUR 1.3 bln – total sector’s volume in Q1-Q3
  • 7/27 portfolio transactions
  • 66% of volume is of US origin

The Polish industrial investment market recorded €1.3 billion in transaction volume in the first three quarters of 2026, marking the strongest year-on-year performance since 2022. Representing 28% of total investment activity, the sector’s volume was generated through 27 completed transactions. Market activity was highly concentrated, with the five largest deals accounting for 56% of total industrial volume. US investors remained the dominant source of capital, participating in all five major transactions and contributing 66% of the sector’s total capital inflow.

This highlights the continued appeal of Polish logistics assets to international institutional investors, particularly those pursuing portfolio acquisitions. Sale & leaseback transactions remained an important market driver, generating €220 million across five deals. While over 70% of volume was concentrated in the Big Five markets, institutional capital was also active in secondary locations.

“Investment activity remains strong, but capital allocation is highly selective. Demand is focused on assets with secure long-term income, while value-add properties continue to attract opportunistic investors. At the same time, sale-and-leaseback transactions have emerged as an important source of investment opportunities in the logistics sector. This market polarisation is likely to remain one of the key trends in the coming quarters.” – Bartłomiej Krzyżak, Co-Head of Investment Department

Office sector – landmark transaction in Warsaw

Sector in numbers:

  • EUR 1.1 bln – total sector’s volume in Q1-Q3 2026
  • 30 transactions
  • The largest single-asset office deal since 2022 recorded in Warsaw

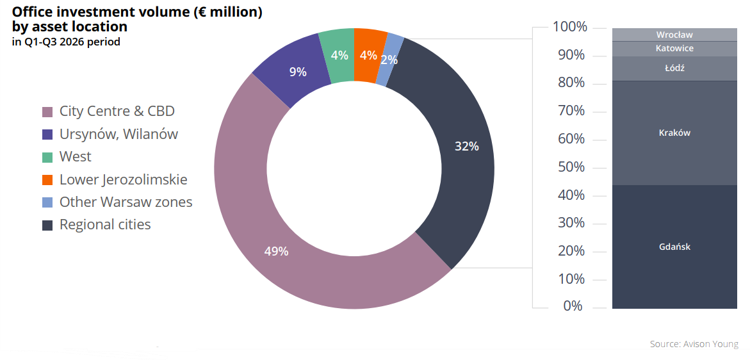
Office sector in Q1-Q3 2026, with its volume build up by single-asset transactions, remained slightly behind other asset classes, contributing 24% of the overall transaction volume. Nevertheless, it recorded 7 prime deals across Warsaw, Kraków and Gdańsk. The most impressive was the acquisition of The Bridge in Warsaw by Eastnine, which was the largest single building transaction since the disposal of Generation Park Y in Q3 2022.

With an average transaction size exceeding €38 million, the Polish office investment market demonstrates a notable degree of depth and diversification. While several high-profile prime transactions have driven headline activity, market liquidity remains supported by a broad base of smaller and mid-sized deals, reflecting sustained investor interest across a range of asset profiles.

Domestic investors accounted for 30% of office investment volume year-to-date, highlighting their continued relevance in the sector. Overall Polish capital is the most active in office segment so far this year.

“The broadening of transaction activity across multiple deal-size categories indicates a clear improvement in liquidity within the Polish office investment market. Investors’ demand remains highly selective, with capital concentrated on assets offering prime locations, modern specifications, strong tenant covenants and long-term value creation potential. Growing interest in regional city opportunities, combined with sustained activity from domestic investors and owner-occupiers, has been complemented by the re-emergence of institutional capital from Western Europe.

While investment activity was largely driven by smaller transactions in recent years, investors are increasingly willing to pursue larger and more prestigious assets. Nevertheless, the market continues to favour best-in-class buildings that meet the highest standards of quality, operational efficiency and sustainability.” – comments Marcin Purgal, Co-Head of Investment Department, Avison Young

EXPO REAL considerations

Investors’ sentiment remains cautious but constructive, with capital continuing to seek opportunities despite ongoing geopolitical and macroeconomic uncertainty as well as rising interest rates across all major markets.

Domestic investors are increasingly capitalising on transactional opportunities, while international capital remains selective, focusing on asset quality, pricing discipline and financing conditions.

Investment decisions are more and more often driven by asset selection rather than risk appetite, with investors prioritising value creation potential, execution certainty and opportunities offering unrealised upside.

Transaction efficiency and process predictability have become key considerations, reflecting a growing preference for investments with lower execution risk and clearer deployment pathways.

Cost and availability of financing becomes key factor in discussions between Sellers and Buyers.

Against this backdrop, the Polish investment market appears well positioned for an active year-end, supported by improving liquidity and a growing pipeline of investment opportunities.